If you’re a GST/HST registrant, every dollar of GST or HST you pay on business purchases is money you can claim back from the CRA. These are called Input Tax Credits (ITCs), and many freelancers — from photographers to ecommerce sellers — either don’t claim them at all or claim them incorrectly. Here’s how to get it right.
What Are Input Tax Credits?
When you buy something for your business — office supplies, software, a client lunch — the vendor charges you GST/HST. As a registered business, you can recover that tax by claiming it as an Input Tax Credit on your GST/HST return.
You buy a $100 printer cartridge in Ontario. The vendor charges $113 ($100 + $13 HST). When you file your GST/HST return, you claim that $13 back. Your actual cost is $100, not $113.
Over a year of business expenses, ITCs add up to hundreds or even thousands of dollars. It’s money that’s yours — you just have to claim it.
Who Qualifies for ITCs?
You can claim ITCs if:
- You’re registered for GST/HST — Either voluntarily or because you’ve crossed the $30,000 threshold
- The purchase was for business use — Not personal
- You have proper documentation — A receipt or invoice with the details the CRA requires for its amount (the vendor’s GST/HST number is required from $100)
- You paid or owe the GST/HST — You can claim ITCs on purchases even before you’ve paid the vendor, as long as you have the invoice
If you’re not registered for GST/HST, you cannot claim ITCs. The GST/HST you pay on purchases is simply a cost of doing business.
The $30,000 Threshold
You must register for GST/HST once your revenue exceeds $30,000 in a single calendar quarter or over four consecutive calendar quarters. But here’s what many people miss: you can register voluntarily even below $30,000.
Why would you register voluntarily?
- You can claim ITCs on all your business purchases — recovering the GST/HST you pay
- You appear more established to clients — especially B2B clients who can claim your invoiced GST/HST as their own ITC
- The math often works in your favour — if your business expenses have significant GST/HST, you may get a net refund
The trade-off: you must charge GST/HST to your clients and file GST/HST returns (annually, quarterly, or monthly). For freelancers selling primarily to businesses (who can claim the GST/HST back), this is almost always worth it.
GST vs HST vs PST: What You Can Claim Back
This is where many freelancers get confused. Canada has three types of sales tax, and they’re not all treated the same:
| Tax | Rate | Can You Claim It Back? |
|---|---|---|
| GST (federal) | 5% | Yes |
| HST (harmonized — ON, NB, NL, NS, PE) | 13–15% (varies; NS is 14% as of April 2025) | Yes (includes federal + provincial) |
| PST (provincial — BC, SK, MB) | 6–7% | No — never recoverable |
| QST (Quebec) | 9.975% | Separate Quebec return only |
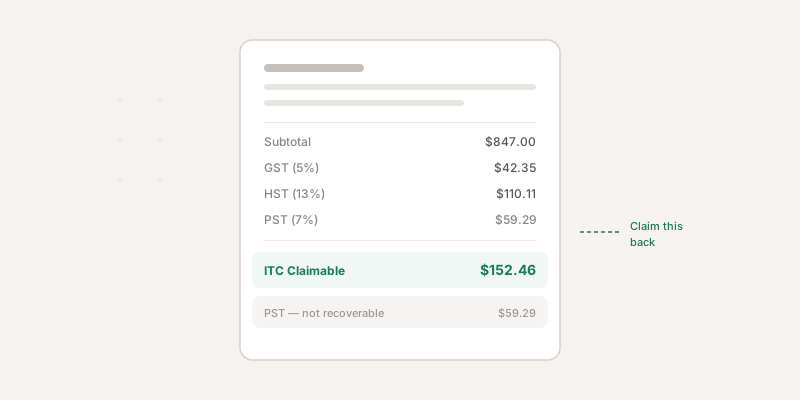
Claiming PST as an ITC. PST is a final tax on the end consumer — businesses cannot recover it. If you’re in BC and pay 7% PST + 5% GST on a purchase, only the 5% GST portion is claimable.
In HST provinces (Ontario, Nova Scotia, etc.), life is simpler — the entire HST amount is claimable as an ITC. Check our provincial tax guides for rates in your province.
How to Calculate ITCs
Fully Business-Use Purchases
If something is 100% for business, claim the full GST/HST:
Purchase: $500 software subscription + $65 HST = $565 total ITC claim: $65
Mixed Personal/Business Purchases
If a purchase is partially personal, only claim the business-use portion:
Purchase: $100/month internet + $13 HST = $113 total Business use: 70% ITC claim: $13 × 70% = $9.10 per month
Common mixed-use items:
- Cell phone — Estimate your business-use percentage honestly (see telephone and utilities)
- Internet — Based on business hours vs total use
- Vehicle — Based on business kilometres vs total kilometres (see motor vehicle expenses)
- Home expenses — Based on the square footage of your home office vs total home (see business-use-of-home)
Meals and Entertainment
Remember the 50% rule for meals and entertainment. For a client lunch:
Purchase: $80 meal + $10.40 HST = $90.40 ITC claim: $10.40 × 50% = $5.20
The 50% limitation applies to the ITC, not just the expense deduction.
Common ITC Mistakes
1. Claiming PST as an ITC
As explained above, PST is not recoverable. Only GST and HST qualify.
2. Missing the 4-Year Deadline
For most registrants, an ITC must be claimed by the due date of the return for the last reporting period that ends within four years after the end of the period in which you could first have claimed it. After that, it’s gone. If you find old receipts with unclaimed GST/HST, you can still claim them on a current return while they’re inside that window. (Note: the limit is two years for listed financial institutions and for businesses whose threshold amount exceeds $6 million in both the current and the previous fiscal year, with some exceptions.)
3. Not Having Proper Documentation
The CRA has three documentation tiers based on the total of the purchase (RC4022, input tax credit information requirements):
- Under $100: the supplier’s business or trading name, the invoice date, and the total amount paid or payable
- $100 to $499.99: all of the above, plus the supplier’s GST/HST registration number, the GST/HST charged (or a note that the price includes it at the applicable rate), and the tax status of each item if taxable and exempt items are mixed
- $500 or more: all of the above, plus your name or business name, a brief description of what you bought, and the terms of payment
Read our full guide on CRA receipt requirements for more detail.
4. Claiming ITCs on Exempt Purchases
Some goods and services are GST/HST-exempt — meaning no GST/HST is charged and therefore there’s nothing to claim. Common exempt items include:
- Basic groceries
- Medical services
- Most financial services
- Residential rent
- Educational services
If no GST/HST was charged on the receipt, there’s no ITC to claim. Don’t invent one.
5. Forgetting About Zero-Rated Supplies
Zero-rated is different from exempt. Zero-rated goods (like basic groceries and prescription drugs) have GST/HST at 0% — the vendor charges $0 in tax, but you can still claim ITCs on your own purchases related to producing them. This mainly matters if you sell zero-rated goods.
Home Office ITCs
If you work from home, you can claim ITCs on the GST/HST portion of home expenses, prorated by your home office percentage.
How to calculate your home office percentage: Divide the square footage of your dedicated workspace by the total square footage of your home.
Your home office is 150 sq ft out of a 1,200 sq ft home = 12.5%. Apply that percentage to the HST on your internet, utilities, and other eligible home expenses.
Eligible home expenses for ITC purposes:
| Expense | ITC Claimable? | Notes |
|---|---|---|
| Internet | Yes | 12.5% of HST portion |
| Utilities (electricity, gas) | Yes | 12.5% of HST portion |
| Home insurance | No | Not typically subject to GST/HST |
| Rent | No | Residential rent is GST/HST-exempt |
| Property tax | No | Not subject to GST/HST |
| Mortgage interest | No | No GST/HST component |
Quick Method vs Regular Method
When filing your GST/HST return, you can choose between two methods:
Regular Method
Calculate GST/HST collected from clients, subtract your ITCs, and remit the difference. This is the standard approach and makes sense when your expenses (and therefore ITCs) are significant.
Quick Method
You remit a set percentage of your GST/HST-included sales (rates vary by province and business type) instead of tracking every ITC. You cannot claim ITCs on operating expenses under the Quick Method, but you can still claim them on certain purchases such as land and capital property you claim CCA on, like computers, vehicles and equipment (RC4022, quick method).
When Quick Method wins: If your business expenses are low relative to revenue (e.g., IT consulting with minimal overhead), the Quick Method’s lower remittance rate means you keep more money.
When Regular Method wins: If you have significant expenses with GST/HST (equipment, supplies, subcontractors), claiming full ITCs gives you a better result.
Run the numbers for your specific situation. Many accountants can tell you in five minutes which method saves you more.
The hardest part of claiming ITCs isn’t the math — it’s the record-keeping. ScanForTax automatically extracts the tax breakdown from every receipt you scan. Our AI separates GST, HST, PST, and QST into distinct fields, so when it’s time to file your GST/HST return, you can see exactly how much you’re owed in ITCs — no manual addition, no missed claims.
Key Takeaways
- If you’re GST/HST registered, every dollar of GST/HST on business purchases is claimable
- PST is never recoverable — only GST and HST qualify for ITCs
- Keep receipts with the vendor’s GST/HST number for every claim
- You have 4 years to claim missed ITCs — check your old receipts
- Mixed-use purchases (phone, internet, vehicle) require honest business-use apportionment
- Compare the Quick Method vs Regular Method annually to maximize your benefit
- Voluntary GST/HST registration often makes sense even below $30,000 in revenue
This article is for informational purposes only and does not constitute legal, financial, or tax advice. GST/HST rules and rates change — always verify current requirements at canada.ca and consult a qualified tax professional for advice specific to your situation.